


“We must believe before we can doubt, and doubt before we can deny.” – W. H. Auden
Hey everyone! I hope you’re all doing well. A short email today (but lots of charts) as I’m catching up on what I missed in my time away from the desk – and my messages are lighting up on the news that Spain’s PM has called snap elections. A smart move, but one with high stakes. 🍃
IN THIS NEWSLETTER
Coming up this week: quiet on the macro front
Macro: A self-fulfilling tension?
BTC: surprising resilience
Crypto is Macro Now offers ~daily commentary and updates on crypto’s evolving role in the changing geopolitical and financial landscapes. Plus links and more.
If you’re a premium subscriber, thank you so much!! ❤
PUBLISHED IN PARTNERSHIP WITH: ✨ ALLIUM ✨
Bloomberg has a new stablecoin dashboard (RWAS <GO>), powered by Allium! It features supply, mints, burns, transfers and velocity, updated hourly, for all stablecoins with over $100m circulating supply, and some smaller and non-USD tokens.
Get weekly onchain data and analysis from the Allium Research team on Substack.

WHAT I’M WATCHING
Coming up this week: quiet on the macro front
Today, we get S&P Global and ISM gauges of services activity in the US and other regions.
And Tokyo hosts a blockchain summit focused on institutional onchain finance.
On Wednesday, TOKEN2049 – one of the world’s major crypto conferences – kicks off in Singapore.
Also, we get the New York Fed’s consumer survey, which will give us an idea as to shifts in inflation expectations.
And we get the minutes from the latest FOMC meeting, which could influence expectations of a rate hike in September.
Finally, on Friday, we get the latest University of Michigan Consumer Survey.
Macro: A self-fulfilling tension?
Time for a macro roundup as a lot happened last week that will no doubt set the stage for this one…
US jobs
First, the US jobs market delivered its monthly barrage of data points, which cumulatively suggest that things are not terrible, but not as strong as everyone thought after the previous set.
Rather than the expected net payrolls gain of 89,000, the official US September report came in with a much softer net gain of 29,000, while that for August was revised down from 162,000 to 133,000.
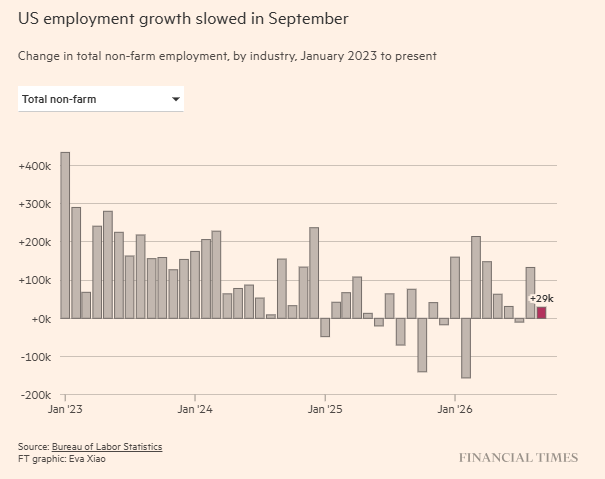
(chart via the Financial Times)
Monthly jobs data can be noisy, however – on a three- and six-month average, the payrolls data still looks strong.
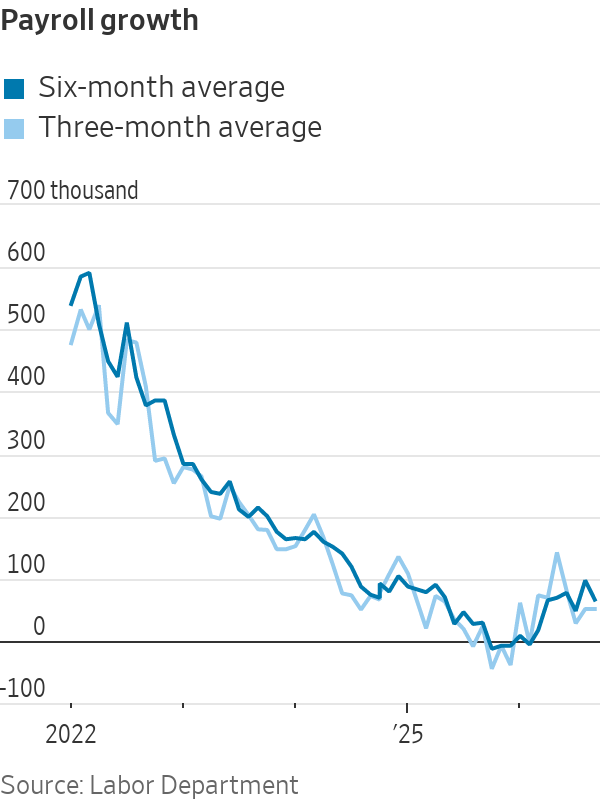
(chart via @NickTimiraos)
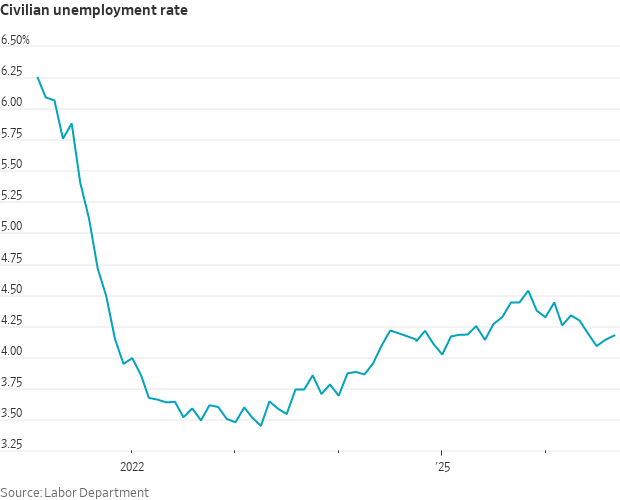
The unemployment rate ticked up slightly, from 4.1% to 4.2%, still comfortably “stable”.
(chart via @NickTimiraos)
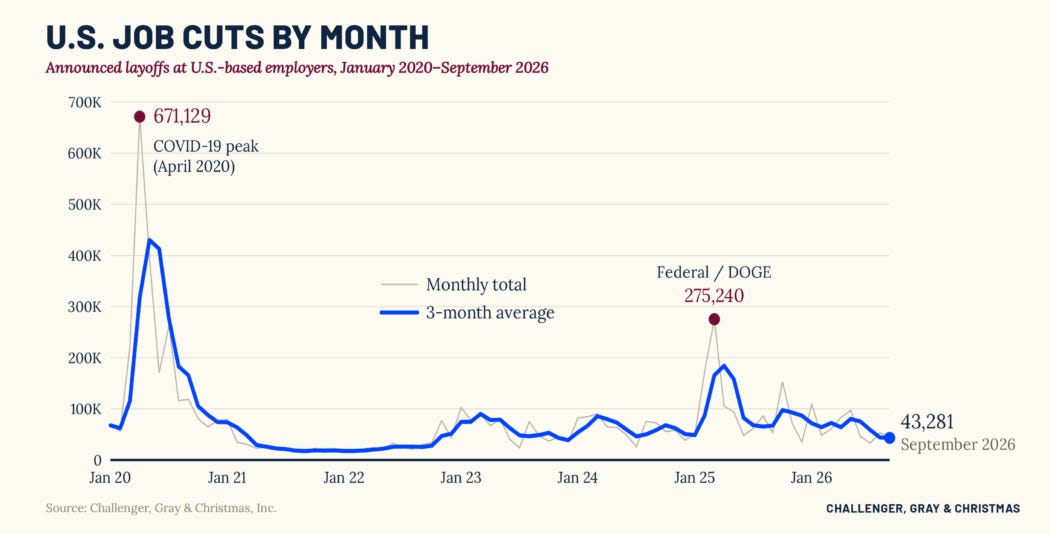
And last week’s Challenger, Gray & Christmas layoffs report showed that the rate of US job cuts has fallen to its lowest level since the tight job market of 2022.
(chart via Challenger, Gray & Christmas)
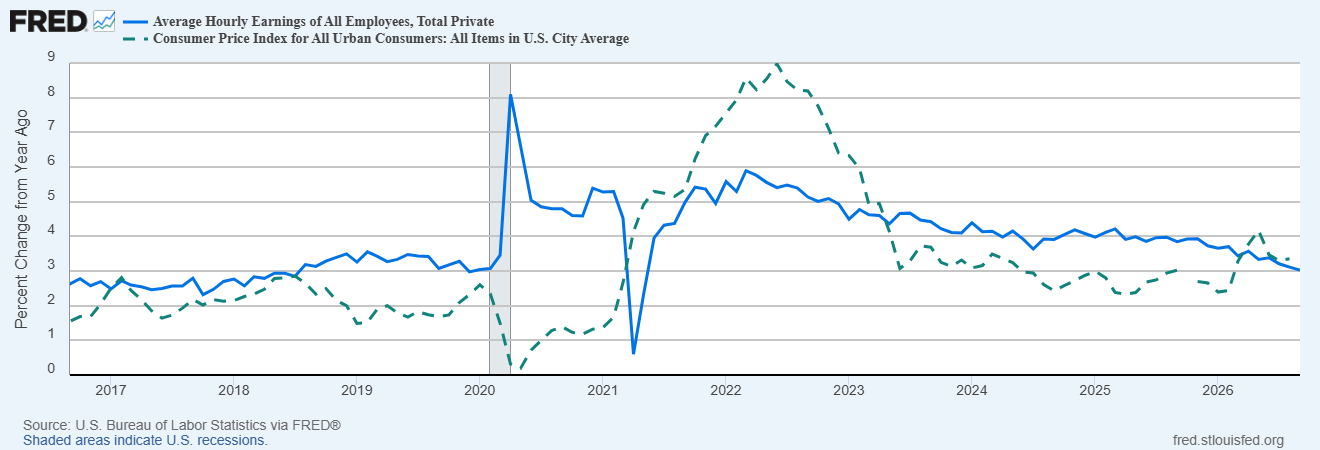
There is one gathering cloud, however: the growth in average hourly earnings extended its decline, slipping further to 3.0%, below the expected 3.2% and August’s 3.1%. If September’s headline inflation data comes in with a more than 3.0% growth, this would mark the sixth consecutive month in which average wages are losing in real terms – not at all good for consumer confidence.
(chart via the St. Louis Fed)
US consumer confidence
Speaking of which, last week we also got the US Conference Board’s report on consumer confidence. No surprise, it continued its downward drift, reaching the lowest level since 2014.
