


“The street finds its own uses for things.” – William Gibson
Hello everyone! I hope you had a good weekend. Got my winter clothes down from storage, and so of course it’s getting warmer here.
Production note: I have a choppy couple of weeks coming up: it’s time for the seasonal vaccinations and the like, so I’ll be skipping publication this Wednesday and also the following.
IN THIS NEWSLETTER
Coming up this week: central banks, macro, geopolitics and mayhem
Monday musings: Sanctions and the tangent threat
Crypto is Macro Now offers ~daily commentary and updates on crypto’s evolving role in the changing geopolitical and financial landscapes. Plus links and more.
If you’re a premium subscriber, thank you!! ❤
PUBLISHED IN PARTNERSHIP WITH: ✨ ALLIUM ✨
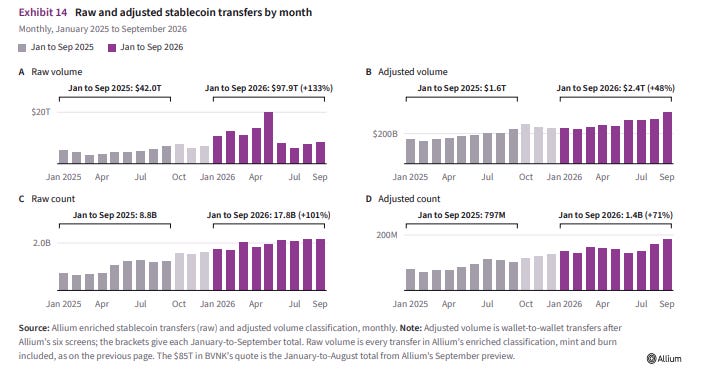
Adjusted stablecoin volume (removing non-economic activity) grew 48% Jan-Sept 2026, despite flat stablecoin supply. The adjusted transfer count grew more than 70%, faster than value, reducing the average transfer size by 14%.
Download Allium’s State of Stablecoins and Payments Q3 2026.
And get weekly onchain data and more analysis like this from the Allium Research team on Substack.

WHAT I’M WATCHING

Coming up this week: central banks, macro, geopolitics and mayhem
Fed decision! And some hefty macro releases. But first, a brief summary of where we’re at as Monday gets going:
The flame under geopolitics has been turned up, and the week is starting out with several big bombshell surprises.
Brazil is reeling after a surprise electoral victory from incumbent President Luiz Inácio Lula da Silva, which – assuming it holds – secures him a record fourth term. Opponent Flávio Bolsonaro has already contested the results, but while there were reported and as-yet-unexplained irregularities, it doesn’t look like he’ll succeed given the margin of his defeat. Markets have gone haywire as Polymarket was pricing a Bolsonaro victory at around 80% - traders were not positioned for this. On today’s open, Brazil’s real fell by more than 12%, and the Ibovespa stock index plummeted 10%, triggering a circuit breaker for the first time since the pandemic freak-out in early 2020.
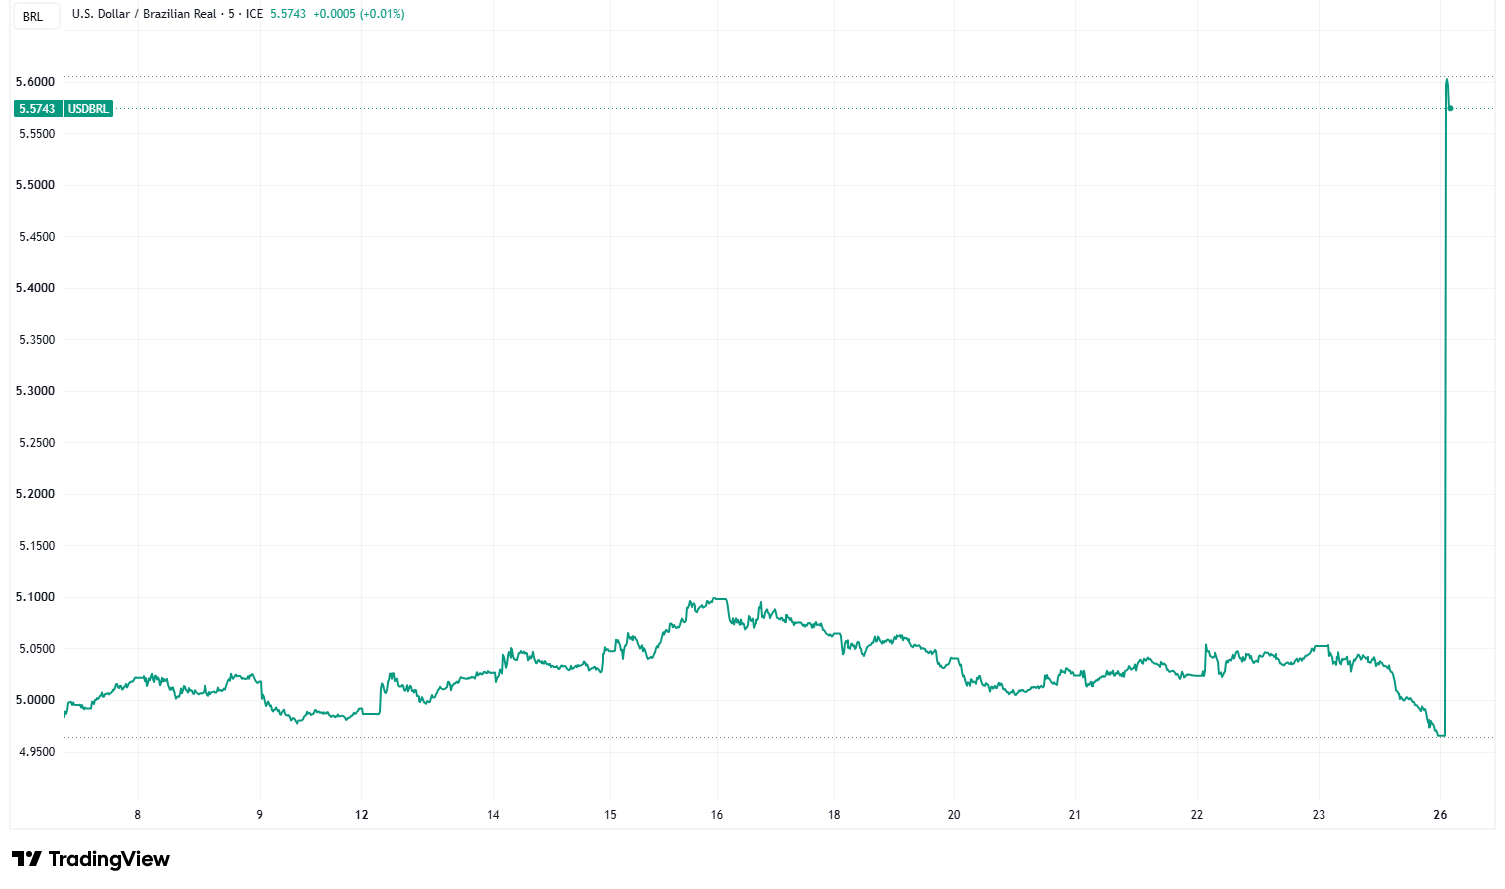
(USD/BRL chart via TradingView)
Another disruption to the global drift to the political right took place yesterday in Serbia, where President Aleksandar Vucic conceded defeat to a student-led protest movement in an election that ended his 12-year rule. A relatively leaderless and young grass-roots movement managed to topple a leader close to Russia, who was often labelled a nationalist and populist “strongman”. Coming so soon after Viktor Orbán’s defeat in Hungary, it heralds both a deep political shift in central Europe, and potential chaos ahead.
Speaking of which, the Wall Street Journal reports that the Trump Administration is pushing Viktor Orbán to enter his candidacy for the role of United Nations Secretary-General. Seriously, this timeline… I really hope Armando Iannucci is taking notes, although he would probably conclude that satire in this era is becoming pointless.
On a more uplifting note: Maria Corina Machado, leader of Venezuela’s opposition party, is back in her country, rekindling talk of a transition to democracy. We can only hope.
Right, on to this week’s calendar…
Today sees the start of China’s Fifth Plenum – I’ll write more about this tomorrow.
On Tuesday, Israel holds Knesset elections which could either unseat its longest-serving prime minister, or give him a clear mandate to continue his military strategy in the region.
Also, we find out how US durable goods orders are doing – forecasts point to a pickup after a few months of month-on-month growth deceleration.
And we get earnings from three stablecoin issuers: PayPal, SoFi Technologies and Robinhood.
On Wednesday, we hear from the FOMC on US interest rates. I agree with the consensus that we’ll get a pause as the inflation temperature is warm but not hot, and as I wrote last week, there are signs we might soon see an AI spending slowdown which will impact economic activity and inflation expectations.
As I type, the CME-priced odds of a hike are only around 10%, while those for another hike in December are almost 70%.
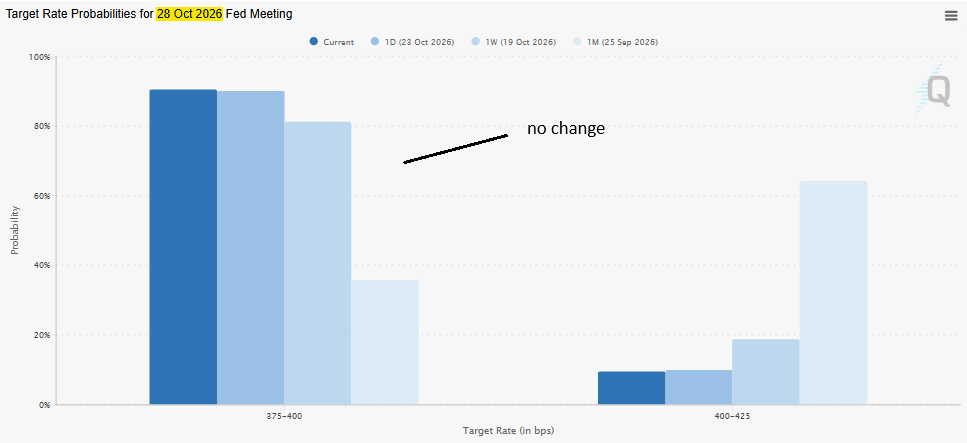
(chart via CME FedWatch)
Also on Wednesday, the UK delivers its first budget under Prime Minister Andy Burnham, which could trigger some market volatility.
The third Russia-Africa summit kicks off in Moscow, to run until Friday. Roughly 2,000 attendees are expected. Among the “priority” topics, according to reports: independent payment systems.
And Alphabet and Microsoft report Q3 earnings.
On Thursday, the ECB decides whether or not to hike rates – if they do, it would be the third hike of the year, but it’s likely they won’t.
Also on Thursday, we get the US Personal Consumption Expenditure report for September, with growth in the core index expected to show a slight acceleration from 3.0% to 3.1%.
We also get the first official estimate of US GDP for Q3 – consensus forecasts point to a jump in growth to 3.2% from the previous quarter’s 2.2%.
Among the companies reporting: Amazon, Mastercard, Intel and Coinbase
On Friday, the Bank of Japan is expected to follow other major economy central banks announcing this week and leave official interest rates as they are.
Plus, we get the first official estimate of EU GDP for Q3, forecast to show a slowdown from 1.2% year-on-year to 1.1%. Slowing GDP growth and climbing inflation… not good.
Also, US Secretary of State Marco Rubio hosts a two-day G20 Foreign Ministers’ Meeting in Atlanta, Georgia
If you find this newsletter at all useful, would you consider sharing it with friends and colleagues and nudging them to sign up? I’d really appreciate it! 🍂
Monday musings: Sanctions and the tangent threat
(what’s on my mind as we head into the week)
One of my guiding principles for this newsletter is to focus on the bigger story, the why rather than the what, and how trends shape changes and vice versa. It’s the reason I don’t do headline summaries or news roundups, even though I’m often tempted – there are so many interesting things happening, so fast, but the noise can easily get overwhelming. And anyway, there are already other newsletters that do that well (I follow BitDigest for general crypto-AI headlines, BlockStories for institution-focused stablecoin/tokenization updates).
Sometimes, though, a single headline can eloquently capture the bigger picture with a real-world example.
Yesterday, while skimming Reuters, I came across the following story:
“Netanyahu rebuked for plan to use crypto to bypass economic sanctions”
Eleven words hint at four major stories, all relevant, all timely, all timeless.
